What is the market overview and industry significance of the Core Making Machine Market?
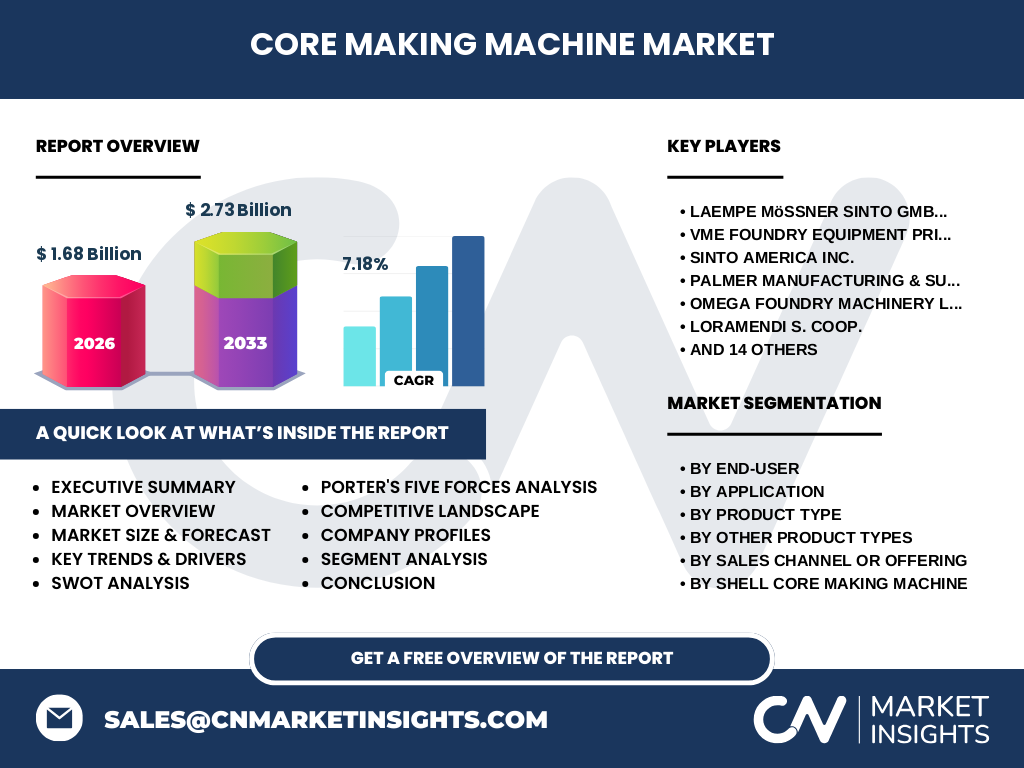
Our analysis indicates that the Core Making Machine Market is valued at 1.68 Billion in 2026, driven by foundry demand for high-precision sand cores. These systems utilize specialized resin-coated sand and advanced core shooter mechanisms to fabricate internal cavities for complex metal castings. Regulatory compliance with OSHA and EPA standards regarding VOC emissions from binder systems dictates machinery design.
Key market drivers, restraints, challenges, and opportunities shaping the Core Making Machine Market
Market expansion is heavily propelled by lightweighting initiatives in automotive manufacturing, requiring complex internal passages. However, high capital expenditure for fully automatic cold box and hot box core making machines acts as a restraint for tier-2 foundries. Opportunities lie in integrating IoT sensors for predictive maintenance, minimizing scrap rates during high-volume aluminum casting processes.
Emerging trends and growth patterns in the Core Making Machine Market
The shift toward additive manufacturing and hybrid core making machines is redefining shop floor efficiency. Foundries increasingly demand gas-heated and electric-heated hot box systems equipped with multi-station shell core capabilities to optimize cycle times. Energy efficiency and minimal binder gas emissions represent critical purchasing criteria for modern procurement managers.
COVID-19 impact analysis and recovery trajectory for the Core Making Machine Market
Pandemic-induced supply chain disruptions caused severe delays in raw material sourcing for heavy machinery manufacturers, temporarily halting foundry expansion projects. Post-COVID recovery has accelerated through automated retrofits and upgrade kits, allowing metal casting plants to address labor shortages by deploying semi-automatic and fully automatic shell core making machines.
Competitive benchmarking and strategic dynamics in the Core Making Machine Market
The competitive landscape features industry leaders like Laempe Mössner Sinto GmbH, Loramendi S. Coop., and DISA Group dominating high-throughput automated lines. Strategic differentiation relies on proprietary core shooter precision and eco-friendly cold box gassing systems. Meanwhile, regional players such as Delin Intelligent Technology compete on cost-effective gravity and resin-coated sand core machines.
Executive summary of key findings in the Core Making Machine Market
Our research projects the Core Making Machine Market to expand from 1.68 Billion in 2026 to reach 2.73 Billion by 2033, registering a robust 7.18% CAGR. Growth is anchored by aerospace and automotive sectors demanding strict metallurgical integrity, favoring suppliers offering comprehensive aftermarket support and versatile hybrid core technology.
Market forecast trajectory from 2027 to 2033
Driven by a projected 7.18% CAGR, the market will scale from 2027 to culminate at 2.73 Billion by 2033. This acceleration reflects sustained capital investments in industrial machinery and heavy manufacturing. Demand for vertical and horizontal cold box units will surge as foundries modernize aging equipment to meet stricter dimensional tolerance thresholds.
Segmentation analysis across end-users, applications, and product types
The market segments by end-user into Foundries, Metal Casting Industries, and Heavy Manufacturing. Applications span Automotive, Aerospace, and Industrial Machinery. Product classifications feature Cold Box, Hot Box, and Shell Core Making Machines, alongside diverse offerings like resin-coated sand and core shooter variants tailored for specialized foundry operations.
Regional market analysis and geographic distribution performance
Geographic performance highlights Asia-Pacific as the primary volume driver due to sprawling automotive hubs in China and India, supported by local manufacturers like Wuxi Xinan Foundry Machinery. North America and Europe prioritize advanced automation, focusing investments on vertical cold box systems and eco-conscious binder reclamation to comply with stringent environmental mandates.
In-depth regional review of key manufacturing and casting hubs
Industrial clusters in Western Europe rely heavily on premium engineering from German innovators like RÖPERWERK and Hüttenes-Albertus for high-integrity automotive block casting. Concurrently, North American foundries leverage robust solutions from Palmer Manufacturing & Supply to streamline heavy industrial machinery production under strict regional labor constraints.
Company profiles and strategic positioning of leading market participants
Major industry participants deploy distinct strategies: Sinto America Inc. and Omega Foundry Machinery Limited focus on turnkey foundry integration and robust aftermarket support. Mingzhi Technology Co. Ltd. pioneers advanced tooling and core shooting solutions, enabling foundries to transition smoothly toward digitalized, high-precision aluminium casting operations.
Porter's Five Forces analysis of the Core Making Machine Market
Bargaining power of buyers is moderate to high due to numerous established machinery brands, forcing vendors to compete on technological differentiation. Threat of substitutes remains low because specialized sand cores are irreplaceable in complex ferrous castings. Supplier power over critical hydraulic and electronic components exerts subtle pressure on equipment margins.
SWOT analysis highlighting strategic strengths and market threats
Strengths include advanced automation and high dimensional accuracy of modern core shooters. Weaknesses involve high initial capital outlays. Opportunities emerge in emerging-market industrialization and green foundry upgrades. Threats encompass macroeconomic volatility and strict environmental regulations governing chemical binder emissions during core production.
Value chain analysis from raw materials to foundry end-users
The value chain initiates with raw steel, electrical components, and specialized resin-coated sand suppliers feeding equipment manufacturers. Core making machine producers then engineer, assemble, and distribute systems through direct sales channels or retrofit kits. End-user foundries utilize these machines to supply precision metal components to automotive and aerospace OEMs.
Investment insights, strategic recommendations, and high-potential areas
Investors should target manufacturers specializing in fully automatic cold box and hybrid core making machines, as these address the acute industry demand for reduced labor reliance and lower emissions. High-potential opportunities also reside in aftermarket retrofit kits that upgrade legacy machinery with modern energy-efficient controls.
Conclusion and key takeaways for stakeholders and investors
The Core Making Machine Market represents a resilient, high-value sector poised to reach 2.73 Billion by 2033. Success in this landscape hinges on technological adaptability, compliance with strict environmental standards, and the ability to provide comprehensive aftermarket support to traditional and modern metal casting facilities.
Research methodology utilizing trade registries, primary interviews, and macroeconomic data
Our baseline estimates are triangulated by combining official customs trade registry data, primary stakeholder interviews with foundry engineering executives, and secondary macroeconomic indicators. We cross-reference machinery shipment logs with regional manufacturing output indices to ensure absolute accuracy in sizing market segments.
Scope of the report, coverage parameters, and analytical limitations
This report covers global revenue performance, volume shipments, and technology adoption trends across cold box, hot box, and shell core systems from 2027 to 2033. Limitations include potential fluctuations in localized raw material costs and unforeseen geopolitical disruptions impacting cross-border heavy machinery logistics and import tariffs.
Recent developments, company announcements, product launches, and strategic partnerships
Recent industry momentum is defined by strategic partnerships focusing on carbon-neutral foundry operations. Key players have launched advanced gas-heated and electric-heated hot box machines featuring real-time diagnostic software, significantly reducing thermal energy consumption and binder waste across major automotive casting lines globally.